
James Gorman and Hiroshi Mikitani are two influential business leaders who built very different careers. Gorman is known for transforming Morgan Stanley into a financial services business with a much larger wealth management operation, while Mikitani founded Rakuten and expanded it from an online shopping platform into a broad digital ecosystem. But what connects them, and why do people search for their names together?
The available corporate biographies and official records reviewed do not establish a direct business partnership between Hiroshi Mikitani and James Gorman. There is no confirmed joint venture or shared company leadership identified in those sources. Their connection is better understood as a comparison between two executives who have led major international businesses in different industries.
That comparison is still worth exploring. Gorman’s experience centers on institutional transformation, financial services, and executive succession. Mikitani’s career is closely tied to entrepreneurship, technology, and building new businesses around an established customer platform. Their experiences reveal two different ways of approaching growth, leadership, and long-term business strategy.
Who Are James Gorman and Hiroshi Mikitani?
James Gorman is an Australian-born American financial executive best known for his leadership at Morgan Stanley. He became the firm’s CEO in January 2010 and served as chairman from 2012 through 2023. After leaving the CEO position, he became executive chairman for 2024 and chairman emeritus in January 2025. He is also chairman of The Walt Disney Company’s board. These roles are documented in Morgan Stanley’s official biography and Disney’s leadership profile.
Gorman’s professional background includes executive positions at Merrill Lynch and a senior partnership at McKinsey & Company. He studied law and earned an MBA from Columbia Business School before building his career in financial services.
Hiroshi Mikitani is a Japanese entrepreneur who founded Rakuten Group in 1997. He remains its chairman, president, and CEO, according to the company’s management information updated in April 2026. Rakuten began with online commerce and subsequently expanded into financial technology, mobile communications, travel, digital content, and other services.
Mikitani studied at Harvard Business School, where he earned an MBA, after beginning his professional career at the Industrial Bank of Japan. His combination of financial experience and entrepreneurial ambition helped shape the way he approached his own company.
Although both men have senior leadership experience, their roles differ considerably. Gorman is an executive with experience guiding established corporations through transformation and succession. Mikitani is a founder who continues to lead the company he created.
What Is the Connection Between James Gorman and Hiroshi Mikitani?
The most important distinction is that a professional comparison does not establish a personal or commercial relationship.
The official leadership pages for Morgan Stanley, Disney, and Rakuten identify Gorman’s and Mikitani’s respective roles, but the sources reviewed do not document a direct partnership between them. That does not prove they have never met or had any indirect contact. It means a specific connection cannot responsibly be presented as a verified fact.
Their names can nevertheless appear together in business discussions because both lead organizations with international reach and complex strategic challenges. Morgan Stanley operates across institutional securities, wealth management, and investment management. Rakuten combines consumer-facing digital services with financial technology and mobile communications.
These businesses offer useful material for comparing corporate leadership. Both require decisions about investment, competition, customer relationships, and future growth. Yet the business models behind those decisions are not the same.
Morgan Stanley operates in a highly regulated financial services environment. Rakuten competes across several digital and financial markets, where technology, customer engagement, and the relationship between services can influence growth.
Therefore, the most defensible way to discuss Hiroshi Mikitani and James Gorman together is to examine their careers and leadership approaches, rather than suggesting an undocumented partnership.
James Gorman’s Career and Morgan Stanley Transformation
Gorman joined Morgan Stanley in February 2006 and was appointed co-president in December 2007. He became CEO in January 2010, at a time when financial institutions were still dealing with the consequences of the global financial crisis.
His leadership involved more than managing daily operations. Morgan Stanley had to strengthen its business model, manage risk, improve its earnings profile, and make decisions about where to invest for future growth.
One important part of Gorman’s strategy was expanding the wealth management business. This helped Morgan Stanley develop a more diversified earnings base, rather than relying so heavily on revenue streams that can fluctuate with trading activity and investment banking conditions.
The firm also expanded through acquisitions, including the integration of Smith Barney, the purchase of E*TRADE, and the acquisition of Eaton Vance. These transactions strengthened different parts of its wealth and investment management operations.
Gorman’s tenure illustrates how leading an established financial institution differs from building a company from scratch. A CEO must work within existing systems, manage regulatory obligations, satisfy shareholders, retain employees, and make strategic changes without undermining the company’s core operations.
His time at Morgan Stanley also made succession planning a significant part of his legacy.
Expansion of Wealth Management
Wealth management became a central part of Morgan Stanley’s business under Gorman. The division serves individuals, families, businesses, and other clients seeking financial planning, investment advice, portfolio services, and related solutions.
This business has a different revenue profile from institutional investment banking. Wealth management can generate recurring revenue from client relationships and assets under management, although earnings still respond to financial markets, interest rates, client activity, and other economic conditions.
The acquisition of E*TRADE in 2020 strengthened Morgan Stanley’s position in digital investing and self-directed brokerage services. The Eaton Vance acquisition, completed in 2021, expanded its investment management capabilities.
Together with the firm’s existing wealth management operations, these deals helped Morgan Stanley serve a wider range of clients. The strategy also connected different parts of the business: investment advice, digital account access, financial planning, and investment products.
The key point is not that wealth management eliminates financial risk. Rather, it gives a company more than one source of revenue and allows different services to support a broader client relationship.
Gorman’s approach is a useful example of institutional transformation through a combination of acquisitions, operating strategy, and gradual business development.
Gorman’s Succession at Morgan Stanley
Gorman’s departure from the CEO role was a major leadership transition for Morgan Stanley. He announced his intention to step down in 2023, and Ted Pick succeeded him as CEO in January 2024.
Gorman continued as executive chairman for the remainder of 2024 before becoming chairman emeritus in January 2025. This transition allowed the firm to separate day-to-day executive management from the experience and oversight provided by a departing CEO.
Succession is especially important at large financial institutions. Investors, employees, clients, and regulators need confidence that a change in leadership won’t disrupt the business or weaken its strategic direction.
A planned transition can give an incoming CEO time to establish priorities while preserving continuity in the board’s oversight. It also gives the outgoing leader a defined path away from executive responsibilities.
Gorman’s succession is relevant to the comparison with Mikitani because it highlights different leadership circumstances. Gorman helped prepare a large established corporation for a new CEO. Mikitani, by contrast, remains at the head of the company he founded.
Neither model is universally better. A founder-led business and a publicly traded financial institution face different challenges, and their governance needs naturally differ.
James Gorman’s Role at Disney
Gorman became chairman of The Walt Disney Company’s board on January 2, 2025. His current position, as reflected in Disney’s leadership information during 2026, is a board leadership role rather than the company’s CEO position.
His financial services background gives him experience in corporate governance, executive oversight, major strategic decisions, and leadership succession. These are relevant responsibilities for a board chairman at a large entertainment company with businesses spanning films, television, streaming, sports, and theme parks.
Disney’s 2026 CEO transition illustrates the importance of board involvement in leadership planning. In February 2026, Disney announced that Josh D’Amaro would succeed Robert A. Iger as CEO, with the transition scheduled for the company’s annual meeting in March.
Gorman’s responsibility as chairman includes helping the board carry out its oversight role, including evaluating leadership and supporting long-term strategy. That does not mean he personally manages the company’s daily entertainment operations.
His Disney position adds another dimension to his career. He has moved from leading a financial services organization to overseeing the board of a global entertainment company, applying experience in governance and executive leadership to a different industry.
Who Is Hiroshi Mikitani?
Hiroshi Mikitani is the Japanese entrepreneur who founded Rakuten Group in February 1997. He remains its chairman, president, and CEO.
Before launching Rakuten, Mikitani worked at the Industrial Bank of Japan. He later studied at Harvard Business School, earning an MBA in 1993. His background combines financial knowledge with an interest in entrepreneurship and the commercial possibilities of the internet.
Rakuten Ichiba, the company’s Japanese online marketplace, launched in May 1997. The original idea was to create an online environment where merchants could reach customers without needing to build a large independent retail operation.
Over time, Mikitani expanded the business beyond online shopping. Rakuten moved into financial services, travel, digital content, telecommunications, and other areas. These businesses increasingly became part of a wider ecosystem built around the company’s customer relationships and membership services.
Unlike Gorman, who joined a well-established financial institution and later helped transform it, Mikitani built a business from its early stages. He has remained closely associated with its strategy as it expanded into new industries and international markets.
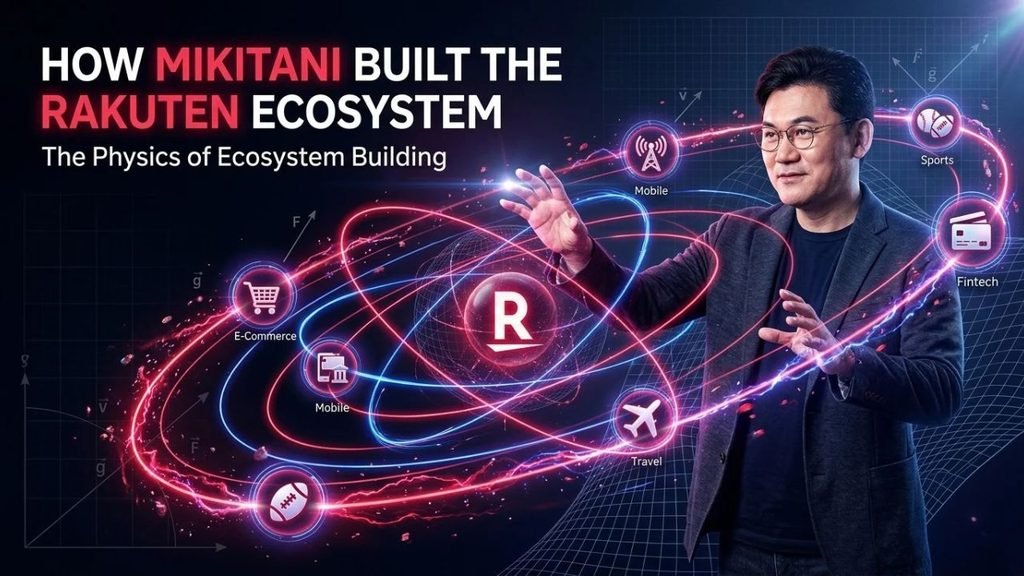
How Mikitani Built the Rakuten Ecosystem
Rakuten’s development was based on extending an online marketplace into a wider collection of digital services. Instead of treating every business as a separate relationship with customers, the group built connections between services that could encourage customers to remain within the broader ecosystem.
Its business areas include online retail, travel services, digital content, financial products, and mobile telecommunications. The company also operates services that connect users with payment options, banking, credit cards, and investment platforms.
This strategy creates potential advantages. A customer who shops through Rakuten may also use its points program, payment services, financial products, or travel platform. The company can use its existing relationships to introduce other services and encourage repeat engagement.
The approach also creates challenges. Each business has its own operating costs, regulatory requirements, competitors, and investment needs. Expanding into a new sector can increase the company’s reach, but it can also consume capital for years before the business becomes consistently profitable.
Rakuten’s history demonstrates both sides of founder-led expansion. It has created a broad presence across several industries, but certain operations, particularly mobile telecommunications, have required significant investment. The group must continually balance expansion with financial discipline.
Expansion Into Fintech and Mobile Services
Financial technology is an important part of Rakuten’s business model. Its financial services include Rakuten Bank, Rakuten Card, Rakuten Securities, and insurance-related operations.
These businesses connect customers to services such as banking accounts, payments, credit cards, investments, and insurance. The wider ecosystem can help Rakuten introduce customers to additional services while strengthening the relationship between the company’s different platforms.
Mobile telecommunications represented another major strategic expansion. Building a mobile network requires substantial investment in infrastructure, service quality, customer acquisition, and ongoing operations.
The business can support the wider ecosystem by bringing mobile subscribers into Rakuten’s services, but subscriber growth alone does not guarantee profitability. Revenue, capital expenditure, operating costs, and customer retention all matter.
Rakuten’s own financial updates show that the mobile business has been working to reduce losses while growing revenue and subscribers. That makes it a useful example of the difference between expanding a business and establishing sustainable profits.
Mikitani’s strategy reflects an entrepreneurial willingness to enter new markets, but its results also demonstrate why diversification must be accompanied by financial discipline and clear operational priorities.
Rakuten’s Current Financial Position
Rakuten’s latest available quarterly results during October 2026 are for the second quarter of fiscal 2026, released on August 10, 2026.
According to the company’s official Q2 FY2026 financial results, Rakuten reported quarterly consolidated revenue of ¥665.5 billion, up 11.6% year over year. IFRS operating income reached ¥20.0 billion, an increase of 126.9%, while net income attributable to the parent company’s owners was ¥7.7 billion. Rakuten described this as its first quarterly net profit at that level in six years.
These results show an improvement in the group’s financial position, but a single profitable quarter doesn’t establish that every business is consistently profitable or that all financial pressures have disappeared.
The company’s full-year 2025 results provide another useful perspective. Rakuten reported revenue of approximately ¥2.497 trillion and IFRS operating income of ¥14.382 billion. It nevertheless recorded a net loss attributable to owners of approximately ¥177.886 billion.
Those figures come from Rakuten’s 2025 full-year financial disclosure. The difference between operating income and net income matters: financial expenses, taxes, and other items can affect the final result even when a company generates positive operating income.
The latest quarterly performance offers encouraging signs, particularly across internet services and fintech, but Rakuten still faces the challenge of converting its scale and ecosystem into sustained profitability across the group.
Mikitani’s Ownership Position
Mikitani is Rakuten’s founder and its chairman, president, and CEO. He also holds a significant personal shareholding in the company, although he does not personally own all of Rakuten.
According to Rakuten’s official shareholding information, as of December 31, 2025, Mikitani personally held approximately 8.14% of the company’s shares. The same disclosure lists Crimson Group, LLC, separately, with approximately 10.43%.
These figures can be checked in Rakuten’s official shareholder information.
Share ownership is relevant because it gives context to a founder’s relationship with a public company. However, ownership percentage, voting arrangements, and executive responsibilities are not identical concepts. Mikitani’s leadership position and his personal shareholding should therefore be understood separately.
It is also important not to confuse ownership with net worth. His personal wealth can be affected by the market value of shares and other assets, liabilities, and investments. A shareholding disclosure alone doesn’t provide a complete or current calculation of his total wealth.
James Gorman and Hiroshi Mikitani: Two Leadership Models
Gorman and Mikitani offer two different examples of senior business leadership. Their experiences overlap in areas such as strategy, international markets, and long-term planning, but the environments in which they operate are quite different.
Gorman led Morgan Stanley through a significant period of institutional transformation. His work involved strengthening wealth management, overseeing acquisitions, managing risk, and preparing the company for a CEO transition. His later role as Disney chairman also reflects a focus on board governance and leadership oversight.
Mikitani’s work centers on building and expanding Rakuten. His strategy has involved creating new businesses, entering new markets, connecting different services, and maintaining a founder-led approach to corporate development.
The difference is partly structural. A large financial institution must prioritize regulatory compliance, client confidence, capital management, and succession planning. A technology-oriented group operating across multiple sectors must balance innovation, customer growth, infrastructure investment, and profitability.
Neither executive’s approach can be reduced to a simple formula. Their decisions have been shaped by their industries, companies, competitive environments, and responsibilities.
Gorman: Institutional Transformation
Gorman’s experience illustrates how a leader can change an established company without abandoning its core purpose. Morgan Stanley’s expansion in wealth management and investment management diversified its business, while the transition to Ted Pick demonstrated an organized approach to succession.
Institutional transformation requires coordination across large teams and existing systems. Leaders must assess which businesses should grow, where capital should be invested, and how changes affect clients, employees, and shareholders.
The results of any transformation need to be evaluated over time. Acquisitions can expand a company’s capabilities, but integration, operating costs, and market conditions influence whether they deliver lasting value.
Gorman’s career provides an example of executive leadership shaped by established corporate structures and formal governance.
Mikitani: Founder-Led Expansion
Mikitani’s approach illustrates the opportunities and risks of founder-led expansion. As Rakuten’s founder, he has been closely involved in developing new businesses and shaping the company’s broader strategy.
The ecosystem model creates opportunities to connect shopping, financial products, mobile services, and digital platforms. If customers use several related services, the group may strengthen engagement and increase the value of each customer relationship.
However, expansion into many industries can make management more complex. Investment in telecommunications, for example, has different economics from an online marketplace or credit card business. A strong performance in one segment may not automatically offset losses elsewhere.
Mikitani’s experience shows how entrepreneurship can create a broad business platform, but also why growth must eventually be matched by consistent financial performance.
What They Have in Common
Despite working in different industries, Gorman and Mikitani share several broad leadership challenges.
Both have been responsible for companies operating at an international scale. Their decisions affect employees, customers, investors, and business partners across multiple markets.
Both have also had to consider long-term investment. Morgan Stanley’s expansion in wealth management required strategic acquisitions and sustained integration, while Rakuten’s digital ecosystem and mobile network required investment in technology, services, and customer relationships.
Another shared theme is organizational change. Gorman managed a transition in the leadership of Morgan Stanley, while Mikitani has guided Rakuten through expansions into new business areas.
Their experiences also show the importance of measuring outcomes rather than relying on growth narratives alone. Revenue, operating income, customer engagement, risk, and leadership continuity all matter when assessing the performance of a large organization.
These similarities make their careers useful to compare, but they don’t establish that the executives share a personal relationship or have collaborated directly.
Major Differences Between Gorman and Mikitani
The clearest difference lies in their professional starting points and the organizations they lead.
Gorman built much of his reputation as an executive within established financial institutions. He joined Morgan Stanley in 2006, became CEO in 2010, and helped reshape the firm’s business mix before preparing for succession. His current work as Disney’s board chairman reflects experience in corporate governance rather than responsibility for running Disney’s daily operations.
Mikitani, on the other hand, founded Rakuten in 1997 and has remained its central executive leader. His focus has been on creating businesses, entering new markets, and linking services together under a common ecosystem.
Their industries also create different risks. Financial services depend heavily on regulation, market conditions, capital, and customer confidence. Digital commerce and telecommunications involve competition, technology investment, customer acquisition, and infrastructure costs.
Finally, their leadership situations differ. Gorman’s Morgan Stanley CEO tenure ended with a planned transition to a successor. Mikitani continues to lead the company he founded, which places founder leadership and corporate governance at the center of questions about Rakuten’s future.
Why the James Gorman and Hiroshi Mikitani Comparison Matters
Comparing these executives helps explain why there is no single model for successful business leadership.
Gorman’s career demonstrates the complexity of transforming a mature financial institution. His emphasis on business diversification, acquisitions, and succession planning offers lessons for leaders responsible for large organizations with established clients and regulatory obligations.
Mikitani’s career shows a different route: creating a company around an internet marketplace and expanding into related businesses as opportunities emerge. His approach highlights the potential advantages of connected services, alongside the financial and operational challenges of managing a wide ecosystem.
The comparison also encourages readers to separate genuine connections from interesting parallels. Two executives may have similar responsibilities or face related strategic questions without being partners, friends, or collaborators.
For investors, students, business leaders, and readers interested in corporate strategy, that distinction is valuable. It keeps the discussion grounded in documented facts while still allowing meaningful analysis of how companies grow and change.
Frequently Asked Questions
Who are these two business leaders?
James Gorman is a financial executive who led Morgan Stanley as CEO from 2010 to 2023 and is chairman of Disney’s board. Hiroshi Mikitani is the founder, chairman, president, and CEO of Rakuten Group.
What companies are they associated with?
Gorman is associated most prominently with Morgan Stanley and The Walt Disney Company. Mikitani is associated with Rakuten Group, the Japanese digital services and e-commerce company he founded in 1997.
What is James Gorman known for?
Gorman is known for leading Morgan Stanley through a period of major business transformation, especially its expansion in wealth management. He is also known for his role in planning the leadership transition at Morgan Stanley and subsequently becoming Disney’s board chairman.
What is Hiroshi Mikitani known for?
Mikitani is known for founding Rakuten and expanding it beyond online retail into financial services, telecommunications, travel, and digital content. His leadership has shaped Rakuten’s strategy of connecting multiple services within a broader business ecosystem.
Are they connected professionally?
The official corporate biographies reviewed do not establish a direct business partnership between Gorman and Mikitani. Their careers can be compared meaningfully, but a specific joint venture or formal working relationship has not been verified in the sources reviewed.
Do they have similar leadership backgrounds?
They share experience leading large international businesses, but their backgrounds differ. Gorman’s career emphasizes institutional management and corporate transformation, while Mikitani’s centers on entrepreneurship and founder-led expansion.
Why are these two names mentioned together?
Their names may be discussed together in business commentary because both have led major organizations and faced complex questions involving strategy, investment, growth, and leadership. That comparison doesn’t necessarily indicate a direct personal or commercial relationship.
Conclusion
The story of Hiroshi Mikitani and James Gorman is best understood as a comparison between two distinct approaches to business leadership, not as a confirmed partnership. Gorman’s career highlights institutional transformation, wealth management, and succession planning. Mikitani’s career reflects entrepreneurship and the expansion of Rakuten into a broad digital and financial services ecosystem.
Their paths differ, but both show how major organizations must balance growth, investment, financial performance, and long-term strategy. Rakuten’s latest results illustrate the opportunities and challenges of building a multi-business platform, while Gorman’s career demonstrates the demands of transforming an established financial institution and overseeing corporate leadership.
The key takeaway is simple: there is value in comparing their strategies, but the available evidence does not establish a direct business connection between them. Keeping that distinction clear produces a more accurate and useful account of both leaders.